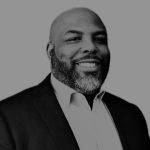
We had the opportunity to host Kyle Brown, CEO, and Ben Malcolmson, Head of Investor Relations at Trinity Capital (NYSE: TRIN), for an investor call with a group of institutional investors.
A few things stood out:
- Five unique verticals give Trinity a diversified platform while maintaining specialized expertise across its investment strategies.
- Alignment matters! Trinity is an internally managed BDC and does not pay a management fee to an external manager, which keeps management’s interests closely aligned with shareholders.
- Credit quality continues to stand out. Across 44 BDCs analyzed by Reuters, non-accruals increased from 2.5% to 3.4% of portfolio cost during the first half of 2026 – not for Trinity.
At Trinity, the trend moved in the opposite direction: non-accruals were just 0.8% of the debt portfolio in Q2, down from 1.1% in Q1.
***That’s an important distinction in today’s private credit environment.***
Thank you to Kyle and Ben for an engaging discussion and for sharing their perspective on Trinity’s platform, the BDC landscape, and the opportunities ahead.
Learn more about Trinity Capital here.